
Do You Need 20% Down To Buy a House?
Nathan Ide
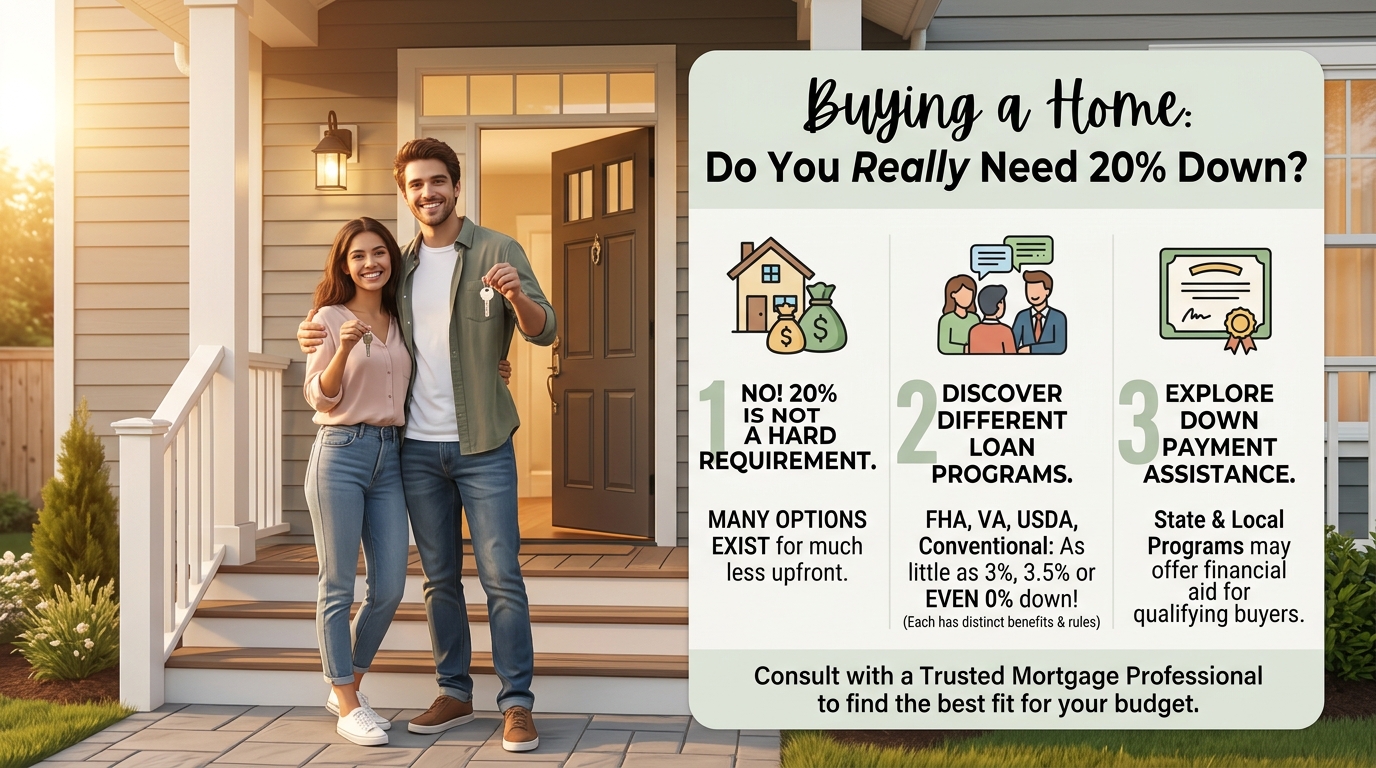
You do not necessarily need a 20% down payment to buy a house in Michigan. While putting more money down can lower your loan amount and may help you avoid private mortgage insurance, many qualified homebuyers purchase with far less. At Ideal Mortgage Services, LLC, we help buyers throughout Haslett, Lansing, East Lansing, Okemos, Mason, and the surrounding Greater Lansing communities compare mortgage options that fit their budget and goals.
For many buyers, the belief that they must save 20% before starting the homebuying process becomes an unnecessary delay. The right down payment depends on the loan program, your qualifications, your available savings, and the monthly payment you can comfortably manage. A mortgage pre-approval can help bring those details into focus.
Understanding the available mortgage loan programs in Michigan can replace assumptions with a clearer plan for buying a home.
Why So Many Buyers Think They Need 20% Down
The 20% down payment guideline has been repeated for years, but it is not a universal requirement for getting a mortgage. It is better understood as one option that can offer certain advantages rather than a mandatory threshold every buyer must reach.
A larger down payment reduces the amount you borrow. Because the mortgage balance is lower, the monthly principal and interest payment may be lower as well. Over time, borrowing less can also reduce the total cost of financing the home.
With a conventional loan, a down payment of 20% or more can generally allow a borrower to avoid private mortgage insurance, commonly called PMI. Since PMI is an added monthly expense, avoiding it may improve monthly affordability.
Putting more money down can also support favorable mortgage terms for some borrowers. These are meaningful benefits, which is why a larger down payment is often recommended when it fits a buyer’s financial plan. Still, those benefits do not mean 20% is required to purchase a home.
Many Michigan Homebuyers Put Down Less Than 20%
It is common for first-time buyers to enter homeownership without reaching the 20% mark. In fact, the average first-time homebuyer puts down about 10%, showing that a much smaller upfront contribution can still lead to a successful purchase.
Every buyer has different financial priorities. One person may prefer to keep an emergency fund after closing, while another may need to account for moving expenses, existing debt, furnishings, or early home maintenance needs. Using every dollar of savings for a down payment is not always the most comfortable or sustainable choice.
Instead of concentrating on one percentage, it is helpful to look at the complete financial picture. That includes the cash needed at closing, estimated monthly mortgage payment, ongoing household expenses, and the funds you want to retain after buying a home.
Ideal Mortgage Services works with Michigan homebuyers to review those tradeoffs. As a wholesale mortgage broker, we can shop multiple lenders and provide a clearer side-by-side look at financing options rather than limiting the conversation to a single loan product.
Loan Programs Can Make Buying a Home More Accessible
Mortgage eligibility is not based only on the amount you have saved for a down payment. Lenders also consider factors such as income, credit history, debt obligations, and your overall financial stability.
Today’s mortgage programs recognize that a ready buyer may have solid qualifications without having years to set aside a large down payment. Although a larger contribution can reduce long-term borrowing costs, lower-down-payment programs can help qualified buyers move forward sooner.
That flexibility matters for people who are ready to buy in Lansing, East Lansing, Haslett, Okemos, Mason, or other Michigan communities but do not want to postpone their plans solely to reach 20%. The most appropriate loan is the one that aligns with your qualifications and supports your longer-term financial goals.
When you request mortgage advice from Ideal Mortgage Services, LLC, our team can explain the available choices in straightforward terms and help you see how each option may affect upfront costs and future payments.
FHA Loans May Require as Little as 3.5% Down
Federal Housing Administration loans, commonly known as FHA loans, are among the best-known options for buyers seeking a lower down payment. Qualified borrowers may be able to purchase a home with as little as 3.5% down.
For Michigan buyers with dependable income but limited savings, that lower requirement can make homeownership feel more attainable. It can also allow buyers to keep funds available for moving, furnishings, maintenance, and other expenses that can arise after closing.
FHA financing has its own eligibility standards and costs, just as every mortgage program does. However, the ability to buy with a smaller down payment has made FHA loans an important path for many first-time homebuyers in Michigan.
At Ideal Mortgage Services, we can help you compare an FHA loan with other mortgage options so you understand the differences in down payment, monthly costs, and overall fit before making a decision.
VA and USDA Loans May Offer Zero-Down Options
Some eligible borrowers may have access to mortgage programs that do not require a traditional down payment. VA and USDA loans can provide qualified applicants the opportunity to finance up to 100% of a home’s purchase price.
VA home loans are designed for eligible veterans, service members, and other qualifying borrowers. USDA loans are intended for eligible buyers and properties that meet the program’s requirements. Each program has specific qualification guidelines, so it is important to confirm eligibility before relying on a zero-down option.
For the buyers who qualify, these programs can significantly reduce the upfront cash needed to buy a home. They can be especially valuable when a borrower has the income and credit to support a mortgage payment but wants to preserve savings for other priorities.
Our team can help Michigan homebuyers review VA, USDA, conventional, and FHA loan programs and determine which options deserve a closer look based on their individual circumstances.
Your Best Down Payment Depends on Your Financial Plan
Meeting a program’s minimum down payment requirement is only one part of the decision. The amount you choose to put down should also reflect your comfort with the resulting monthly payment and your plans after closing.
Some buyers choose a larger down payment because they want a smaller loan balance and lower monthly mortgage costs. Others decide to put less down so they can maintain cash reserves for emergencies, repairs, furniture, or other financial needs.
Neither approach is automatically right for everyone. The ideal amount depends on your financial profile, your long-term priorities, and what feels manageable for your household.
It is important to weigh upfront spending against ongoing affordability. A mortgage calculator can be a useful starting point, but a personalized discussion can provide a more complete view of estimated payments, closing costs, and available loan programs.
Start With a Michigan Mortgage Pre-Approval
If you have been waiting to buy because you thought 20% down was mandatory, a mortgage pre-approval may be the right next step. Pre-approval gives you a clearer understanding of your potential borrowing range and the programs for which you may qualify.
It also allows you to explore how different down payment amounts could affect your monthly mortgage payment. Rather than guessing, you can make decisions using information that reflects your income, credit, debts, and homebuying goals.
Ideal Mortgage Services, LLC serves homebuyers across Greater Lansing and throughout Michigan with purchase mortgages, mortgage rate quotes, and pre-approval guidance. We shop multiple lenders, explain the options clearly, and stay accessible throughout the process.
You may be closer to homeownership than you think. Contact Ideal Mortgage Services at 517-303-3012 or visit us at 1257 Haslett Rd, Haslett, MI 48840 to explore your Michigan mortgage options and find a down payment strategy that works for you.